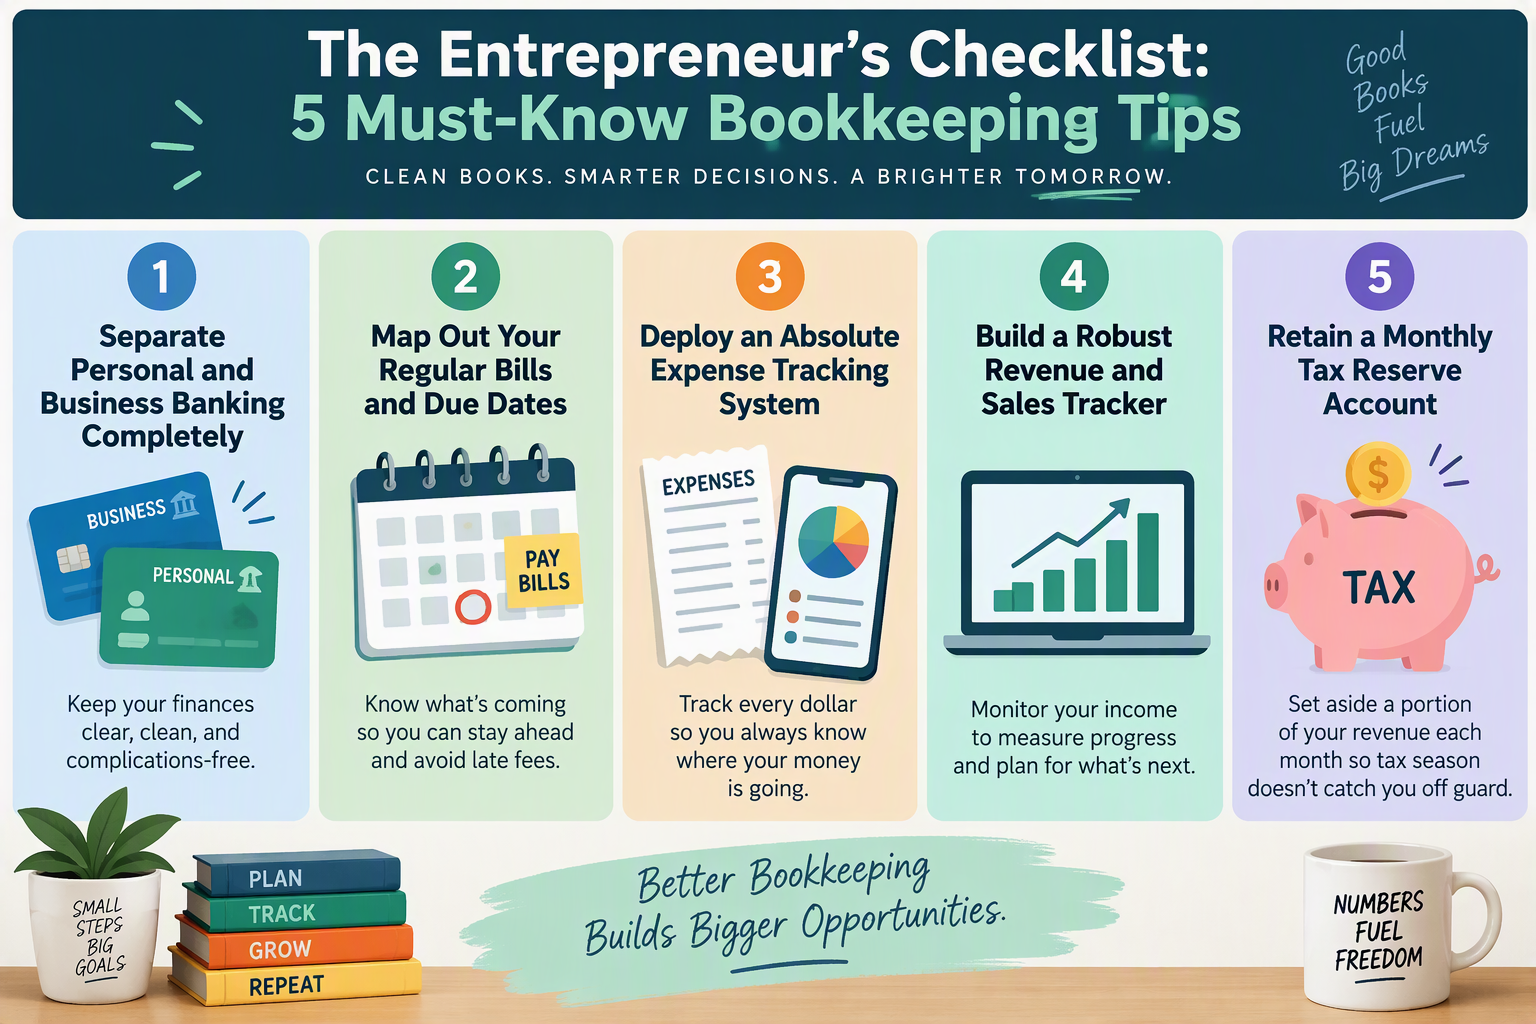
The Entrepreneur’s Checklist: 5 Must-Know Bookkeeping Tips
Bookkeeping is a foundational element of running a business, but it can easily overwhelm new entrepreneurs. Without clear systems, tracking operational data quickly turns chaotic.
Implementing basic structured routines shields your company from cash crunches. Here are five non-negotiable bookkeeping habits every business owner must adopt to stay on the road to long-term success.
1. Separate Personal and Business Banking Completely
Co-mingling your funds is an immediate bottleneck for financial tracking. Using a single account for both coffee runs and client invoices makes it incredibly difficult to identify your actual profitability.
The Rule: Establish a dedicated corporate checking account and a separate business credit card immediately.
The Payoff: This separation cleanly isolates your business transactions, streamlines month-end reconciliation, and saves your accountant hours of work during tax preparation.
2. Map Out Your Regular Bills and Due Dates
Missing vendor payments or utility deadlines results in costly late fees and disrupts your daily supply chain.
The System: Maintain a centralized rolling ledger or digital calendar strictly for fixed overhead costs like rent, software subscriptions, insurance, and recurring vendor bills.
The Payoff: Knowing exactly when capital is leaving your account ensures you always maintain adequate working capital to cover liabilities on time.
3. Deploy an Absolute Expense Tracking System
Every dollar spent running your company must be meticulously logged. This covers overhead costs, office supplies, travel miles, and specialized equipment.
The System: Never rely on memory. Use mobile receipt scanning or accounting software to track and categorize outflows immediately.
The Payoff: Accurate expense tracking provides a realistic view of your monthly burn rate and guarantees you capture every legal write-off to reduce your tax bill.
4. Build a Robust Revenue and Sales Tracker
Understanding your cash inflows is just as vital as watching your expenses. You must know exactly which products, services, or clients generate your highest profit margins.
The System: Set up a structured pipeline to track outgoing invoices, client payment timelines, and incoming daily cash sales.
The Payoff: Monitoring your income trends helps you identify seasonal slowdowns early and highlights opportunities to aggressively scale your most profitable offers.
5. Retain a Monthly Tax Reserve Account
Tax obligations should never be an afterthought. Waiting until the end of the fiscal year to calculate your tax liability can lead to severe operational cash shortages and penalties.
The System: Automatically transfer a fixed percentage of your monthly gross revenue into a dedicated, untouched business savings account.
The Payoff: Creating this predictable buffer ensures you can confidently meet your state and federal tax liabilities without draining your working capital.
Master Your Finances by Delegating to the Experts
Building these habits takes consistent effort and a sharp attention to detail. As a business owner, your focus should be on building client relationships and driving innovation—not spending your weekends balancing spreadsheets.
If managing your daily transactions is pulling you away from high-level growth, outsourcing your ledger to an expert is the ultimate strategic move.
Contact Poe Bookkeeping Today to set up a consultation. Let our certified team streamline your daily accounting workflows so you can focus entirely on driving your business toward massive success.